Friday, November 3, 2017

The curious case of Intellect Design Arena

It's the annual report season and among the many companies that we read about this one particularly caught our attention. The company we will discuss about is Intellect Design Arena (IDA). Before talking about this further I would like to draw attention to this particular extract from their investor presentation for FY17 available on their website

 
Here is a company which currently is loss making on an operational level and talks about 
  • Improving Operating margins from a loss to 26% in FY20
  • Changing revenue mix from low margin implementation to high margin License & AMC
  • Revenue growth guidance till FY20 of over 20%
Its a mandatory exercise to check past track record of a management which is giving such lofty projections for the future. When we looked at what Intellect has delivered in the past, this is what we found


In his interviews Arun Jain promises a growth in revenues of 20-25% over the coming years. Since listing IDA has delivered on the lower point of 20%.

However this has come at a cost


The company has an extended working capital cycle with receivable days around 6 months. Though the quantum has been coming down and management has mentioned in latest reports of focusing more on collections and hence the days of receivables outstanding over next few years would be a key operating metric to track

Business Model
 
IDA is a software company dealing in the products vertical which develops and implements product suites for the financial sector. To understand the business further here is some more information:


Intellect is present across four broad verticals i.e. iGCB(Global consumer banking), iGTB(Global transaction banking), iRTM(risk, treasury and markets) and iSEEC(Insurance). Within each domain, the company offers a variety of products that cater to specific needs of the consumer


Here is some information on how business evolution develops for a product company 
 
in.PNG 
A product company's life cycle can be broken into four parts - incubation (product building), catalyst (Customer reference building), adoption and monetization. Intellect currently has products across different stages in the cycle and as they move from reference building to adoption and ultimately monetization, the company will start enjoying the full benefits of operating leverage.

The management further goes on to say that every additional dollar of revenue earned will add 60 cents to the bottom line implying a net profit margin of over 60% on incremental business

All of this information is available in the company presentations put up on the website by the company

How does a company like IDA bill revenue

The revenue component for software companies is broken down into broad headings - the first being License & AMC Fee and the second being Implementation/Services fee. Besides this, there is a general practice of booking unbilled revenues The magnitude of which varies from company to company with global leaders like Temenos clocking in 80% of their revenues in the form of License & AMC Fee.
Note - Companies tend to partner with System Integrators for  implementation of their software once they've achieved a certain scale. For instance, Temenos only partnered with third party's once it had started clocking $400mn in annual revenues - until then, all integration is done in house.)

 Here is a chart from the company presentation depicting revenue mix and its change for IDA

revenue breakdown.PNG 

After going through how the company earns let us understand what and ow much it needs to spend to earn its revenue


Being a young software product company, Intellect has to spend a considerable amount of its revenue on marketing its product to the mass market, the benefits of which accrue with time. In the past two years, the company has spent 32% of its revenues on sales & marketing. Here is a trend of how sales & marketing have moved in the past

We cross checked to see whether high expenditures are a norm in the sector. Because there is no similar competitor in India we looked at global peers, the leader being Temenos, a Swiss company


Another significant expense that software companies have to recognize on a recurring basis is high R&D - in terms of both product maintenance and new product development. The industry wide norm in case of development expenses is to capitalize them and subsequently amortize over a period of ten years. On the other hand, maintenance expenses are treated as an individual line item and deducted from revenues

Intellect spends close to 13% of revenues on R&D and has started capitalizing development expenses from FY'17 onwards. This has led to intangible assets on the balance sheet increasing from 32cr in FY'16 to 133cr in FY'17.  Management guides for this trend to continue as R&D remains an integral part of running the business. The subsequent capitalization allowed IDA to post operating profits over the last two quarters. It remains to be understood that if this was the industry norm why wasn't IDA following the same from the start

   
There is not too much to understand from the past numbers of a loss making company and hence we tried to find out what is the opportunity pie for a company like IDA. To understand what's in store we read through what the leader was saying about the sector. Since there is no like to like competitor for IDA in the Indian markets we looked at the global leader Temenos.

Here is what Temenos had to say


In it's annual report of 2014, Temenos - a global software provider talked about the withering moat of the banking  sector. Traditionally, banking has been a difficult business to penetrate across economies due to high levels of regulatory compliance and extensive infrastructure spend required to setup a bank from scratch. "Getting a license, setting up branch network and spending on setting up the core network entails a substantial amount of capital and time - two precious and scarce resources available to mankind". It is this precise reason as to why banks on an average clocked RoE's in the region of 15-17% between 1990 and 2008


 What is changing...


The rapid strides made by technology in terms of un-bundling the entire banking experience into a single click of an app have opened up the floodgates for a host of agile fintech companies to garner incremental market share away from these once indomitable institutions The growing need of "banking as an experience" and the propensity of millennials to switch service providers has prompted banks to increasingly focus on upgrading their core legacy systems to match new competition and at the same time, cater to the fast evolving demand patterns of their customers


So What stops banks from adapting to new technologies?
A case study conducted by Ernst and Young concluded that core replacement for banks is a high risk affair characterized by lengthy delivery cycles and costs. Due to this, decisions to replace core platforms are being constantly deferred in the face of uncertainty and potential system disruption. Instead, what banks prefer is  letting their legacy core systems run on the background and upgrading the front end to digital which helps them achieve the best of both worlds - enhanced customer service experience without having to transform the core platform


Here is what Arun Jain "promoter of IDA" has to say about the changing landscape of the IT industry


 So to conclude we can see that
  • IT industry is changing from a service play to a product play
  • Opportunity size is huge as reiterated by the global leader
  • Legacy platforms remain and hence opportunity lies in newer markets

Even though IDA is a business that got recently listed it has been in business for long when Polaris acquired the products division of Citibank and hence operating history for the company spans more than a decade

We looked at the past numbers of IDA and found some observations which warrants deeper attention:

Raising debt on books


 Bringing out a rights issue to pay off a  recurring revenue line item and general purposes

 
(in Rs million)  

Another question that comes in mind after the recently concluded rights issue that Intellect has carried out is:
  • Despite having cash to the tune of 116cr on books, why would the company feel the need to dilute equity especially when as much as 25% of the proceeds of the issue are to be expended for "general corporate purposes." 
  • What use would the 84cr lying in current accounts be of

 From a net cash company on being de merged from Polaris to now a net debt position to having to raise a right issue. All in two years. The financial footing does not seem to be too strong for IDA. This makes us think as to was it a good idea to separate IDA from Polaris considering the desperate financial support IDA warrants every quarter.

 The management mentions itself that there is a huge upside for the. Have a look at this extract from their interview

 
With the future being so bright as certified by the management we assumed management must be holding majority stake in the company. However the current shareholding looks like this


The promoter holds 31% in the company, which is pretty much off the maximum permissible 75% allowed. I was assuming management having majority stake considering
  • Future looks very bright
  • Promoter must be flush with cash considering sale of Polaris
However we can see that the promoters have been increasing stake over the last quarter so we tried to analyze what the promoter has done over the last two years since listing


As we can see in the above image the promoters have not added any stake to their overall shareholding over the last two years. During Sep 2016 two promoter entities got de classified which led to a reduction and over the last quarter the promoter has bought shares which shows us why there is an increase over last quarter. What i could conclude is that even though the promoters are very bullish on the business prospects, they have not backed that up with meaningful buying in the company shares

To conclude

  • We need to keep a track on receivable days to measure if management is walking the talk on collections
  • any increase in stake by promoter considering extremely bright prospects of company in near future
  • improvement in operating metrics without any accounting adjustment 
  • fund flow due to the difficult financial situation IDA seems to be in 

(Disclaimer : We have positions in the above mentioned stock and our views are likely to be biased as a result. This post should not be treated as a buy/sell recommendation. We are not SEBI Registered Investment Advisers nor Research Analysts.)

Saturday, September 2, 2017

Learnings from Kodak and Fujifilm

How it used to be in the earlier days...
Back in the twentieth century, the market for chemical based photographic processes was dominated by a single player. The industry hadn't changed much in over a hundred years and any in-roads that amateurs made was through their distribution and not innovation. Either ways, taking on Eastman Kodak wasn't an easy task by any mean.
and then, what innovation did..
The oil embargo and soaring inflation of the seventies led to an astronomical rise in silver prices - a key ingredient in the film processing industry. Incumbents such as Eastman and Fujifilm found business incredibly hard to come by , though this ultimately proved to be a mere passing shower rather than a full fledged storm. However in the midst of all of the turbulence, Minoru Ohnishi - the then CEO of Fuji Photo was already preparing for a tsunami of change that the industry was about to witness. In 1984. Sony launched its path breaking digital camera - Mavica. In the ensuing 15 years, Fuji spent nearly $ 2bn in R&D to ramp up on digital photography. The result? Fuji gained almost all of the incremental market share in digital picture processing - it had 5,000 labs across the globe. Eastman Kodak was now where Fuji was twenty years back - it could muster up a mere 100 labs

The above illustration has been plucked from Rita Gunter McGrath's book on competitive advantage. The basic premise that the book has been written on is that competitive advantages for any company cannot sustain over long periods of time. Even though I would not totally agree on that premise, however, in the context of this post we will use it as a reference point. Take for instance the case of RIM - the company that manufactures the now obsolete Blackberry handsets. Blackberry had become the choice of the masses - from businessmen to savvy youngsters, everyone wanted a piece of the glam. Today, the company fights for its mere existence. The cause for decline? Complacency.

How status quo is changing...
A thought provoking idea for any investor/entrepreneur stems from the fact of defining the word 'competition.' Consensus believes that competition comes from rivals selling similar products within the same industry. However, companies today face competition from within the same industry as well as from external forces that threaten to substitute the very validity of existing business models. Sandeep Engineer(the promoter of Astral Poly) in one of his speeches alluded to how he pushed the use of C-PVC pipes as an alternative to traditionally used Galvanized Iron pipes in industries - a classic example of one business model fighting it out against the other. Till then, plastic pipes were an anomaly, today it's the order of the day. This serves us an example of how business models can change and the earlier indications are slow, unnoticeable. However, complacency is the breeding ground for competition to take over and snatch what earlier was yours. Companies & Industries that have understood this have flourished, while those who didn't have rightly become extinct.

What competition is doing today and how to survive...
In today's world, disruption is the catch phrase of the masses. So much so that savvy investors and entrepreneurs live by it. Consensus believes that incumbents across business lines will find it increasingly difficult to cope up with the pace of disruption and legacy business models are no longer tailor made to sustain longsighted growth as seen in the past. Today, you'd find most stories on how businesses are driving themselves to extinction like Kodak did because management teams have failed to deploy capital productively in an environment of transient advantages.

Professor McGrath in her book shares her observations regarding certain companies who have successfully navigated disruptions in their businesses to emerge with stronger and more durable moats. She states that one of the patterns to look for in organizations  that have mastered transient advantage environments is the way they continuously free up resources from old legacy advantages in order to fund the development of future ones - with the one goal of earning higher/stable returns on incremental capital employed. In simple words, they abhor status quo, creating an organization, agile enough to adapt. This in turn leads to longevity.

In the light of the above points, I would like to discuss about a company that bears an uncanny resemblance to the points mentioned above:

-being a leader in an ageing business,
-generating significant cash flows
-re-deploying those cash flows into businesses earning  higher incremental returns on capital employed.
 
SRF Limited:

One of the hallmarks of a good management team is that they are masters of disengagement - "the process of moving out of an exhausted opportunity". This is as core to their skill set as is innovation, growth and exploitation of new business avenues. These management teams continuously evaluate business areas and any early warning signs are paid heed to, rather than ignored.

Being a market leader in an ageing industry is a daunting proposition for any management team. Over the years, the market for Nylon Cord Fabric (a key component used in the making of a bias ply tire) has matured to the point of stagnation. Incremental returns have consistently moved lower owing to the widespread shift to radials across the globe.

SRF, the world's second largest maker of the fabric has been no exception to this change. However, let's see what Arun Bharat Ram (Chairman of SRF) has to say in one of his annual letters to shareholders-

Disengagement

Sale of Nylon tire fabrics has traditionally formed the backbone of the technical textiles division in particular and the company at large. In the face of a declining market for its product, the management consciously took a decision to scale down the business to focus on the chemicals and polyester business.

I'll touch upon each of these segments individually:

Notice how Revenue contribution of technical textiles has halved over the years


The bedrock of the chemicals division of the company lies in the application of fluorine for both refrigerant gases and specialty chemicals. The fluorine molecule is one of the most hazardous elements known to man and its handling and application is a highly critical process as it is one of the most chemically reactive elements.
Refrigerant gases are a key component used in cooling devices such as refrigirators and Air-conditioners. SRF is the sole supplier of HFC-134a in India and is the undisputed market leader with a market share of  around 50 percent.

This is what the management had to say in one of the concalls


After establishing itself in the domestic market (annual demand 8,000 tonnes, growing at 12-15%) , SRF has now targeted the American market which imports around 30% of its annual requirement of 110,000 tonnes. Chinese imports of these gases are now subject to an anti dumping duty and SRF is well poised to make deep inroads into the country. The first steps have already been taken as orders from Walmart are witnessing strong traction with time. An 8000 tonnes opportunity in India with a 50 percent market share versus a 33000 tonnes opportunity in the USA tells you that they have barely scratched the surface in this segment.

Specialty Chemicals on the other hand is a R&D driven business wherein the technology to produce a certain set of requirements of global agro chemical and pharmaceutical giants lies solely with the company. Around 80% of revenues come from agro-speciality and the rest from pharma-speciality. SRF over the years has filed for 94 proccess patents and has developed a strong IPR base which enables the company to successfully scale up products that are inherently complex to produce on a large scale.

The company has currently commercialized around 60 molecules and is in the process of developing around 40-50 more through dedicated plants for each molecule (each dedicated plant entails a capex of around 50 to 70cr)

This business enjoys high customer stickiness
due to the critical nature of the product
Packaging as a sector offers a plain vanilla commoditized product with no entry/exit barriers. Its a dull and boring business with miniscule scope of gaining market share through product differentiation or brand recall. As discussed in one of our earlier posts on CCL Products, the only sustainable moat that any commodity centric business can have is cost control - which then reflects in the operating margins of the company.

SRF's packaging division focuses on BOPET and BOPP films that are manufactured in its plants in India and South Africa. This is what Mr Ram has to say about the business in his latest annual letter


Testing management credibility is an important part of the work we do on companies.

Firstly, we took financial data of the past 10 years for SRF's packaging division and its competitiors - Cosmo Films and Jindal Poly to ratify their repeated claims of being the lowest cost producer. The excel sheet is attached below:


The numbers show two things -
one, the hugely volatile nature of the industry, 
two, the margins have been much more consistent and linear for SRF versus competitors over last few years.
One of the technical factors for the above that the management alluded to in a analyst call is that most of the films manufactured are below 12 microns in thickness and are chemically coated. Competitive pressures are relatively lower in this segment as most of the domestic and Chinese capacity manufacture films that are thicker than 12 microns and may/may not be coated.

Secondly.....
The art of creating value for stakeholders is a function of how well one allocates capital. Warren Buffet, in his 1987 letter states that a corollary of efficient capital allocation is that there comes a time when shrinking businesses and extinguishing capital through buybacks is a wiser choice than expanding through acquisitions or capital expenditures. Back in 1997, the domestic NTCF industry was highly fragmented. Companies who made tires had 'backward integration' to make Nylon fabrics as well - a classic case of capital burn because there was no shortage of fabric in the market.

SRF which was then a Rs 283 crore conglomerate acquired CEAT's plant for Rs 325 crores. Ambitious, you might say? Lets look at the demand supply scenario in the domestic market for the next 5 years

(Source - SRF 2001 Annual Report)

The biggest acquisition in India Inc's history back then sparked off a wave of consolidation in the domestic NTCF market which ultimately led to supply side issues as a surplus turned into a deficit. Back then, the company envisioned itself as a consolidator. This is what the management had to say in the Annual report of 2001.


The strong player

Post all the inorganic expansions that were implemented, SRF moved from being the 8th largest NTCF maker in the world to becoming the 2nd largest globally. It has since maintained its position, thereby generating huge amounts of free cash as the business does not require incremental capital to grow(classical Warren Buffett business).

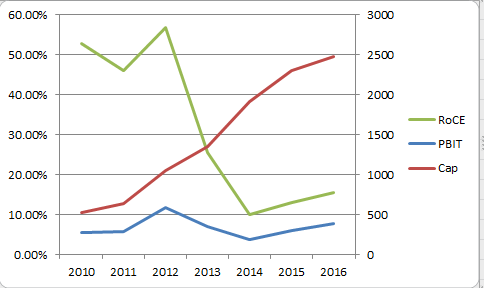
Capital employed and RoCE of technical textiles

So what did SRF do with so much free cash? Lets find out...


Capital employed across all three divisions - Notice how management has built the chemical and packaging business

The tone of the management seems to echo this very fact - that SRF is now positioning itself as predominantly chemical based company and I quote:

“As we announced earlier, we have a plan to invest around INR3,500 crore in the next four years and around 70% of the investments are earmarked for the Chemicals business. Therefore, I would reiterate here, that the chemical space remains a key segment for the Company and our strategic intent to further grow the business remains intact.”

Chemicals RoCE

A closer look at the RoCE graph of the chemicals business reveals that though the management has continuously pumped in incremental growth capital, the RoCE's have fallen from high 50's to 15% as of FY'16 - this is primarily down to the fact that the windfall from carbon credits for the company(which cumulatively amounted to more than Rs 10bn) stopped from FY'14 onwards, thus normalizing returns.


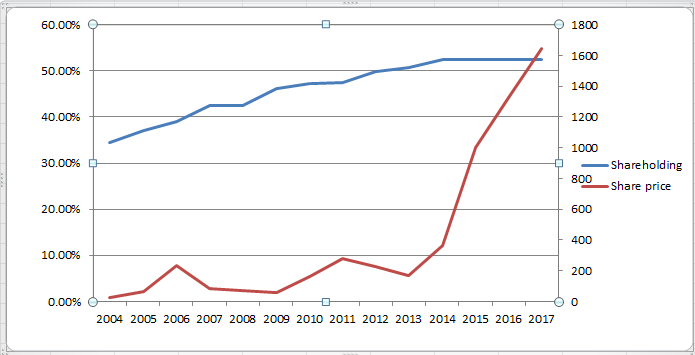
Lastly, we checked for - their skin in the game - we compiled data for the past 13 years to see the change in promoter shareholding. The excel is attached below

SRF's promoters have increased their stake from 34% in 2004 to 52% in 2017

As the moat that protects the castle dries up, it needs to be refurbished so as to protect the kingdom. The management team led by the Ram family have successfully managed to transform SRF's business from being an ageing textile manufacturer to a lean, dynamic and technoogy driven chemical conglomerate.

Ill end by quoting the famous Ben Franklin.
 "When you're finished changing, you're finished."

Thursday, August 31, 2017

What they tell you versus What they dont (Part II)

This post got inspired by something I read on the internet last week. I follow a website on the internet https://25iq.com/
where the author has written a beautiful post on attributes of a scalable business. You can go and read the post from the following link A dozen attributes of a scalable business
One facet from that post caught my attention and i am presenting it here. Please read through the extract (emphasis mine)

  1. Customer acquisition cost (CAC) is low in a scalable business since positive word of mouth is strong (i.e., the business benefits from organic customer acquisition) 
Andy Rachleff believes: “If you don’t have exponential word of mouth growth, you don’t have product/market fit.” In terms of staging a successful startup, product/market fit (which is central to the value hypothesis) should precede scaling (which is central to the growth hypothesis). Spending capital on growth before you have a product that people want to buy is essentially a giant bonfire of cash. Steve Blank talks about why scalability is so important in business: “Success isn’t about size – of team or funding. It turns out premature scaling is the leading cause of hemorrhaging cash in a startup – and death. In fact: (1) The team size of startups that scale prematurely is 3 times bigger than the consistent startups at the same stage; (2) 74% of high growth Internet startups fail due to premature scaling; (3) Startups that scale properly grow about 20 times faster than startups that scale prematurely; and (4) 93% of startups that scale prematurely never break the $100k revenue per month threshold.” Ryan Smith the founder of Qualtrics describes this objective simply: “Nail It, Then Scale It.” Too often people try to scale a start-up before they nail it.
The positive customer word of mouth that Rachleff describes is important for a business since it enables a lower customer acquisition cost (CAC). In other words, scalable businesses generating organic growth do not need massive spending on marketing and sales. Every business will have some customer acquisition costs but in the best and most scalable business that cost is relatively low. Bill Gurley agrees with Rachleff: “With great companies the consumers buy because the product is so good. They aren’t spending [tens of millions] on marketing.” Gurley also believes that customers quality if higher is they are organically acquired: “Organic users typically have a higher NPV, a higher conversion rate, a lower churn, and more satisfied than customers acquired through marketing spend.”
It is important to understand that growth is not always organic from the start of a business. Sometimes critical mass must be achieved in non-scalable ways before a business becomes scalable via organic customer acquisition. Paul Graham points out that sometimes doing what does not scale is essential to enabling critical mass which does allow a business to scale: “One of the most common types of advice we give at Y Combinator is to do things that don’t scale. In Airbnb’s case, these consisted of going door to door in New York, recruiting new users and helping existing ones improve their listings.”


After reading the above post the first thing that came into my mind was the innerwear industry in India and the leader in that sector "Page Industries", the franchisee for Jockey. Now in a consumer facing industry one of the biggest expenses is Customer Acquisition Cost termed as Selling & Distribution Expenses.

One would assume that the leader in the sector would be spending the highest amount on direct selling expenses, both as a percentage of sales and also absolute amounts. Also selling expenses are of three types:

  • Advertisment Expenses (Directly help to build company's brand)
  • Sales Commission & Incentives (Money spent on distributors to push sales)
  • Other Selling Expenses (Indirect/Miscellaneous Selling Expenses)

From the above, one can clearly differentiate between companies having a good brand recall in public versus a company not enjoying a good brand recall. A company spending money on sales commission and incentives implies spending to push sales through distribution channel. A strong brand does not need to give incentives to the distribution channel because products enjoy a recall in the customer's mind.


The following exercise was performed to find how the leading companies stand in the inner wear and leisurewear industry


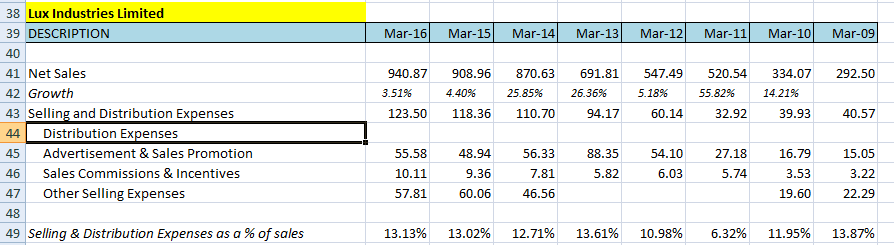
The figures for Lux Industries are for 2016
 
We can note following points from the above:
  1. Page Industries is the market leader with net sales of over rs 2100 crores as on FY17
  2. The two closest competitors viz Rupa & Page do less than half of the revenues of the market leader
  3. Page Industries spent 5.79% of its revenues on Selling & Distribution (S&D) while the same figure for  Rupa & Lux Industries stood at 12.60% & 13.13% respectively.
  4. The  S&D expenses for Page Industries have remained in the range of 5-6% of sales over the last six years while the same for RUPA & Lux has been over in the range of (10-13%) over the same time period
  5. The cumulative amount spent on S&D expenses by the companies over the last 5 years is as under:
  • Page Industries: Rs 415 crores
  • Rupa & Company: Rs 567 crores
  • Lux Industries: Rs 507 crores
As we can see Rupa & Lux over the last five years have spent more on S&D than their competitor Page Industries which  still sells 2 times more than either of these companies, is growing sales at a rate double than these two and has a much better brand recall evident by zero incentives given.

I also tried to see how much each of these companies ell purely on advertisment and the figures are as under
  • Page Industries: Rs 318 crores
  • Rupa & Company Ltd.: Rs 359 crores
  • Lux Industries: Rs 303 crores
All the three companies spend nearly the same amount on advertisement of brand while Rupa still outspends Page Industries by more than 10 percent. However have a look at the next figure and you will know why even after 20 years of page Industries running in the market its competitors still haven't got their strategies right

  • Page Industries: Rs 0.85 crores
  • Rupa & Company: Rs 78.62 crores
  • Lux Industries: Rs 39 crores
The above bullet points show the amounts spent by companies for incentives and commission to distributors. Now what's interesting is that Rupa even after outspending Page Industries on advertisements costs, still pays 8% of its Sales as incentives to distributors.

Its enlightening to know that how good is the S&D strategy for Page Industries versus its competitors where it is able to target its brand effectively, spend lesser amount than its competitors and still keep making the brand stronger year after year. While the strategy that Rupa& Lux follow tells you why the innerwear & leisurewear market has been dominated so effectively by this one brand JOCKEY.

My purpose of this exercise was to show some facts on companies which do simple things everyday that go a long way in creating a sustainable franchisee. Many people would outline the PE of Page Industries or other valuation ratios showing how it is so very expensive versus the other relatively cheaper competitors. However, some time spent in knowing how a company is built, rather than always focusing on price tells you more than what the price of the company on the stock exchanges will show.

Remember the value of a company is the outcome of the work being done behind the scenes. If you focus only on the price you will miss out on a lot...

Thursday, August 24, 2017

What they tell you versus what they don't

This post have been inspired by a recent conundrum which has intrigued many investors. Often people find it difficult to navigate the cycles of stock market and in lack of experience fall prey to following prices.
The individual investor in stock markets will often find people advocating purchase of "lower priced companies".  They wouldn't also be wrong as undervaluation is a big source of long term out performance.
However the idea of purchasing companies with a passionate and ethical management, running a business with a long runway of growth has always intrigued me. I have always seen companies like HDFC Bank, Page Industries, ITC etc delivering returns year after year and what surprises me is that the valuations have always looked expensive.
Thus I thought to study a few of these companies and see whether "undervaluation", which we want while purchasing common stocks have persisted in these companies or not. The first company which I have used while doing this is HDFC Bank. I went through data, annual reports and prices for HDFC Bank since 1996. Below I present you the facts for the bank

Over the last 21 years of its trading history,

Median year end Price to Earnings ratio (1996-2017): 24
Median year end Price to Book ratio (1996-2017): 4.1

I tried to work further with the data to find out if investors could have taken the opportunity of mid year volatility to get better prices. Below are the findings

Median Lowest Price to Earnings ratio from (1996-2017): 16.8
Median Highest Price to Earnings ratio from (1996-2017): 27.5

The lowest valuations experienced by HDFC Bank was in the year 2000 when the mid year Price to Earnings ratio fell to 9.8 times.

Now, I would presume only people who were lucky enough to have insights into business evaluation and also the stomach to buy when price are low could have been able to buy in the year 2000 when valuations were cheap. However, that would have only been a small minority as mere mortals we can hope to make more use of averages than extremes.

For the sake of studying I also wanted to see what If someone bought at the most extreme valuations. How would they have fared? Below I present the facts:

Highest Price to Book ratio (Year 2000): 8.1 times
Stock price as on 31st march 2000: Rs 51.44
Stock prices as on 31st march 2017:  Rs 1442.55

Annual Return over 17 years: 22%

Not bad eh. Even when you would have bought the company at the times when valuations were at historic highs, the returns would have been decent.

The idea of the post is to check whether its always better to look for undervaluation or that every case should be evaluated separately.
In the case of HDFC Bank, even if one would have bought at the extremes they would have generated handsome return. Simultaneously the idea is to look at multiple companies and check whether this idea persists in other companies as well. I would be continuing this practice and would post my findings for the other companies as well.

I have attached the excel sheet if one wants to look at the data. The data prior to 2012 has been adjusted for splits.